Intel Sinks 25% as High-Beta Stocks Slide; Staples Head for Best Month Since 2019
Macro:Intel warned that 2027 free cash flow likely won't be positive and guided fourth-quarter sales below estimates; Amazon missed too. Treasuries are rallying: the 2-year yield fell 9.1 basis points to 4.565% as of 7:24 AM ET.
Market Moves: The S&P 500fell 1.0% and the Russell 20000.5%. Memory chips, South Korea and semiconductors, which led last week's bounce, fell hardest, with memory chips down 6.0%. Consumer staples rose 2.3%.
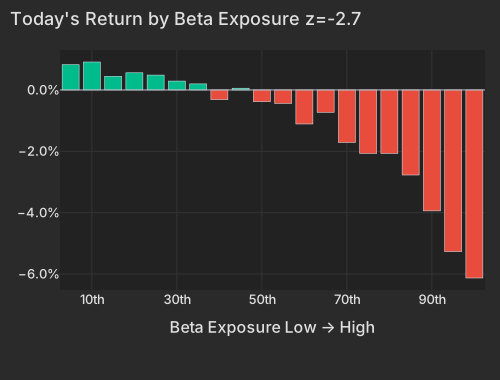
Factors:Beta fell 2.59% (z=-2.7), extending its 20-day slide. The Semiconductors factor fell only 0.64% (z=-1.0), so investors sold market sensitivity, not chip exposure. Style factors explained 56% of stock-level variance, against a 23% one-year average.
Micro:Intelfell 25.2% on a fourth-quarter guidance miss and a warning that 2027 free cash flow likely won't be positive. Sandiskfell 8.7% despite beating, raising guidance and announcing a split; its style exposures account for more than the whole drop.
Watch: Can next week's hardware reports change the read on AI spending? Apple reports Monday, November 2, and AMD on Tuesday, November 3, both after the close.
October 30, 2026 · 07:32 ET · Updated 08:21 ET · pre-market
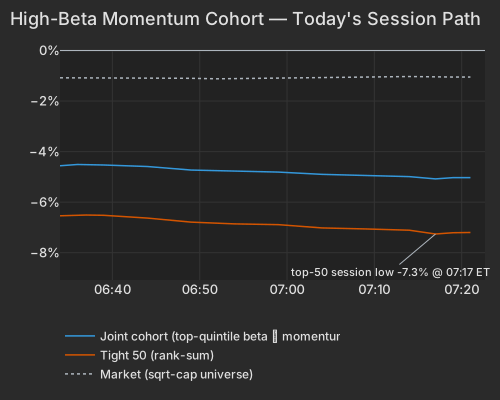
Chipmaker Intelis down 25% in pre-market trading after warning that it probably won't generate positive free cash flow next year, as spending on new factories rises sharply. Its fourth-quarter sales forecast also fell short of estimates, overshadowing a third-quarter beat. Online retailer and cloud provider Amazonis down about 6% after missing profit and revenue forecasts, even though its AWS cloud business grew 39%. The selling is heaviest in the stocks most sensitive to market swings: a basket of 50 high-beta stocks is down about 7%, one of its worst 1.5% of days since 2020, while the rest of the market is roughly flat. The S&P 500is down 1% and the Nasdaq-100about 2.4%.
Chip stocks are falling with them, sorted more by how much they swing with the market than by how much chip business they do. Chipmaker AMD and South Korean memory maker SK hynix are each down about 8%, after South Korea's Kospi fell 3.5% overnight. Flash-memory maker Sandiskis down about 9% even after beating estimates, raising its forecast and announcing an 8-for-1 stock split. Good results have earned little this season: big gains after earnings have been rarer than at this point in any of the past eight seasons. The drop comes after a rough stretch for hedge funds. Goldman Sachs's prime brokerage said systematic long/short funds lost 2% in the week to October 23, their worst week since 2024, as hedge funds cut single-stock positions by the most since late July. A FactorPulse gauge of hedge-fund pain has given back part of its rebound and has now won back only about 13% of its October loss.
Money is moving into steadier corners of the market. The consumer staples fund XLPis up about 2% today and nearly 12% for October, on pace for its best month since 2019. The health care fund XLVis up almost 2%, and snack maker Mondelezis up nearly 9% after its results, though medical-device maker Strykeris down 10% after missing revenue forecasts and cutting its outlook. Treasuries are rallying, with the 10-year yield down about 8 basis points to about 4.9%. Bitcoin is down 4% after crypto exchange Binance reported a $6.3 billion theft. The next test comes at 8:30 a.m., when the Employment Cost Index, a key gauge of wage growth, is expected to show a 0.8% quarterly rise.
Beta is down 2.59% (z=-2.7) so far today and 12.37% over 20 sessions (z=-2.9). It is up just 0.26% over five sessions, so this week's early bounce is gone.
Intel Sinks 25% as Guidance Misses
Intel is down 25.2% in pre-market trading. Its fourth-quarter revenue guidance of $15 billion to $16 billion fell short of estimates Economic Times. CFO David Zinsner said 2027 is unlikely to generate positive free cash flow. He also said capital spending will rise sharply next year after $20 billion in 2026 FinanceFeeds. The third quarter beat estimates, with adjusted earnings of 52 cents a share Economic Times.
Amazon is down about 6% in early trading on light volume. Its overall results missed consensus even though AWS revenue growth sped up to 39% WSJ. For both companies, AI growth was not enough to hold the stock up.
Sandisk shows how much of the damage comes from factors. It is down 8.7% after beating estimates, raising guidance and announcing an 8-for-1 split Investing.com. Its beta and other style exposures account for more than the whole decline, and its stock-specific part is +2.1%. Good results are earning little this season. Weighted by size, 23% of reporters have risen 2σ or more on a stock-specific basis. That is below every one of the past eight seasons at this point.
Earnings reactions in early tradingReporters worth over $100 billion, or moving more than 10% with a value above $5 billion
Stock-specific: the part of a stock's move not explained by the market, style or thematic (industry and theme) factors in the FactorPulse risk model.
Revenue and margin from the company's earnings release, year over year; margin change in percentage points; — where the release is not parsed or the figures failed checks.
† The company's year-ago figure differs from the one originally filed, usually a restatement; growth is on its current basis.
Light volume: the company's earnings filing confirms the report, but trading volume has not caught up yet, so the move is an early read.
Of the 500 largest companies, 271 have reported (58% of market cap), on day 22 of the season.
How earnings reactions split, day 22 of the seasonThe 500 largest US companies with a confirmed earnings reaction so far (243), vs the same day in the past eight seasons and in four-season stretches back to mid-2020
Weighted by size, 23% of this season's reporters rose 2σ or more on a stock-specific basis, against 34% at this point in the past eight seasons; 28% fell 2σ or more (past: 34%).
Earnings reactions this season vs the past eight seasons, day 22
Season
≤ −5σ
−5 to −2σ
−2 to 0σ
0 to 2σ
2 to 5σ
≥ 5σ
This season
9%
19%
26%
22%
20%
4%
Past 8 seasons
15%
18%
16%
17%
18%
16%
Q2 2026
16%
21%
16%
13%
19%
15%
Q1 2026
12%
20%
12%
19%
19%
17%
Q4 2025
17%
17%
20%
14%
18%
14%
Q3 2025
12%
20%
18%
18%
16%
16%
Q2 2025
17%
20%
14%
15%
15%
19%
Q1 2025
18%
12%
15%
22%
22%
11%
Q4 2024
18%
14%
18%
19%
17%
13%
Q3 2024
15%
20%
15%
13%
20%
18%
Q3 '23–Q2 '24
17%
17%
16%
15%
19%
17%
Q3 '22–Q2 '23
12%
19%
19%
18%
20%
11%
Q3 '21–Q2 '22
13%
19%
14%
19%
23%
12%
Q3 '20–Q2 '21
7%
21%
29%
22%
17%
4%
σ: a stock's earnings-day stock-specific move divided by its typical daily stock-specific move over the past year. Each bar is cut at the same business day of the season; companies weighted by the square root of market cap.
Beta Falls 2.6% as Chip Exposure Barely Registers
The Semiconductors factor is down only 0.64% (z=-1.0) on a day Intel lost a quarter of its value. The selling follows market sensitivity, not chip exposure. Chip stocks are falling on their beta. AMD is down 8.4% and SK hynix 7.7%, and their stock-specific moves are small. Asia sold off first, with South Korea's Kospi down 3.5%Morningstar.
Factor
Return
Z-Score
5d Z
20d Z
63d Z
Category
Direction
Beta
-2.59%
-2.7
+0.1
-2.9
-0.9
Style-Risk
High-beta names lagged
Semiconductors
-0.64%
-1.0
+0.9
-1.7
-0.5
Thematic
Chip-exposed names lagged
Liquidity
-0.31%
-1.2
-0.5
-0.5
+0.8
Style
Lowest-turnover names outperformed
Medium-Term Momentum
+0.31%
+1.1
-2.2
-1.1
-0.6
Style-Momentum
Past month's winners beat its losers
One-Day Momentum
+0.30%
+1.1
+0.8
+0.2
-1.7
Style-Momentum
Yesterday's moves continued
Short-Term Momentum
-0.26%
-0.9
-0.6
+1.7
-0.3
Style-Momentum
Last week's winners lagged
Morning Activity
+0.13%
+1.1
-0.6
-0.4
+0.5
Style-Flow
Habitually morning-heavy names outperformed
Hedge-Fund Ownership
-0.09%
-0.8
-0.4
-0.4
-0.8
Style-Positioning
Heavier HF ownership lagged
The losses pile up at the top of the beta range: the highest-beta twentieth of stocks is down 6.1%, led by AI, data-center and memory chip names.
The highest-beta bucket is down 6.1%, with Beta at z=-2.7.
Today's Return by Beta Exposure z=-2.7
Bucket
Avg Ret Pct
1
0.82
2
0.91
3
0.45
4
0.56
5
0.48
6
0.29
7
0.20
8
-0.32
9
0.06
10
-0.38
11
-0.44
12
-1.11
13
-0.73
14
-1.71
15
-2.07
16
-2.07
17
-2.77
18
-3.94
19
-5.27
20
-6.13
The top 50 high-beta momentum names are down 7.2%, in the worst 1.5% of sessions since 2020. The rest of the universe is up 0.02%. The broader high-beta momentum group is down 5.0%, so the more closely a stock fits the profile, the harder it is falling.
The top 50 hit their pre-market low of -7.3% at 07:17 and are running at the 27th-worst of 1,716 days since 2020.
High-Beta Momentum Cohort — Today's Session Path
Series
Ret Pct
joint
-5.04
tight50
-7.22
market
-1.04
rest
0.02
20-day momentum (Medium-Term Momentum in the table) rose 0.31% (z=+1.1) as part of the same selloff: after October's slide, the high-beta names rank among the past month's losers, so their fall lifts this factor. Its five-day z of -2.2 reflects those names' early-week bounce. Yesterday's losers also kept falling: One-Day Momentum rose 0.30% (z=+1.1).
Hedge-Fund Pain Index Has Won Back Only 13%
In its note covering the week to October 23, Goldman Sachs Prime Brokerage reported that systematic long/short funds had their worst week since 2024. The same note showed the heaviest single-stock de-grossing since late July. So far today, our HF de-risking score sits at the 96th percentile since 2020 over 20 days. Two legs are firing: 12-month momentum winners are falling, and last week's relative moves are continuing instead of reverting.
So far today, the hedge-fund pain index has won back about 13% of its fall from the October 6 peak to the October 22 low, down from 20% at Thursday's close. That fall is the 7th-deepest of 32 such events since 2020. Three of eight legs have confirmed a turn, including beta on October 27, but beta is falling again pre-market. The factor pattern is consistent with a de-gross that has not reversed.
On a raw basis, stocks with heavy hedge-fund ownership are lagging by 0.22% (z=-1.5). Net of beta and momentum, the gap shrinks to 0.09%, so these stocks are being hit through their style exposures more than for who owns them.
The pain index has recovered 13% of the loss from its October 6 peak to the low so far on October 22, the 7th-deepest of 32 events since 2020.
HF pain index vs its Oct 6 peak, in daily σ
Date
Sigma Vs Peak
2026-09-24
-1.05
2026-09-25
-0.4
2026-09-28
-0.97
2026-09-29
-0.52
2026-09-30
-0.98
2026-10-01
-0.37
2026-10-02
-0.03
2026-10-05
-0.47
2026-10-06
0.0
2026-10-07
-0.18
2026-10-08
-0.86
2026-10-09
-0.62
2026-10-12
-1.47
2026-10-13
-1.46
2026-10-14
-2.82
2026-10-15
-4.07
2026-10-16
-4.86
2026-10-19
-4.55
2026-10-20
-5.45
2026-10-21
-4.86
2026-10-22
-9.42
2026-10-23
-9.29
2026-10-26
-8.57
2026-10-27
-7.57
2026-10-28
-6.98
2026-10-29
-7.52
2026-10-30
-8.22
Staples Head for Their Best Month Since 2019
Consumer staples (XLP) are up 2.3% today and 11.9% month to date, on pace for the fund's best month since 2019. Health care (XLV) is up 1.7%. Meanwhile, the S&P 500 is down 1.0% and the Nasdaq-100 2.4%. Memory chips, South Korea and semiconductors led last week's bounce and are now falling hardest.
ETF
Theme
Today
1d Ago
5d Ago
20d Ago
63d Ago
DRAM
memory chips & storage
-6.0%
-4.4%
+13.3%
-16.6%
+2.7%
WGMI
crypto miners
-5.3%
-5.2%
+4.3%
-30.0%
-39.6%
EWY
south korea
-4.9%
-2.5%
+8.6%
-13.1%
+3.0%
SMH
semiconductors
-4.8%
-1.1%
+7.3%
-9.1%
+3.9%
MTUM
momentum
-3.2%
-1.7%
+3.4%
-7.0%
-0.2%
QQQ
large cap growth
-2.4%
-1.4%
+1.5%
-3.6%
+4.1%
SPY
large cap
-1.0%
-0.4%
+0.7%
+0.7%
+3.2%
XLE
energy
+1.2%
+0.4%
+1.7%
+9.6%
+16.1%
XLV
healthcare
+1.7%
+2.4%
+1.5%
+10.7%
+13.7%
XLP
consumer staples
+2.3%
+1.5%
-2.0%
+9.8%
+4.4%
Mondelez is up 8.6% after its results, and 3.4% of that gain comes from style exposures, mainly its low beta. Stryker is down 10.0% even as the health care fund rises. Crude is up too, with WTI at $104.24 at 7:14 AM ET, up 2.2%CNBC. Bitcoin is at $77,572 at 7:25 AM ET, down 4.0%CNBC, after Binance reported a $6.3 billion theft Morningstar. The crypto miners fund WGMI is on pace for its second-worst month since 2022.
Treasuries are rallying, and short-dated bonds are leading. The 2-year yield is down 9.1 basis points to 4.565% CNBC. The 10-year yield is at 4.908%, down 8.1 basis points CNBC. Over the past 20 sessions, SMH fell about 9% while the 10-year yield dropped about 25 basis points. Chip stocks have moved this closely with yields only rarely since 2019. Corporate bonds are lagging the rally, a sign that credit spreads are widening again. LQD is up 0.3%, about 0.4% less than the drop in yields alone implies, and HYG is flat.
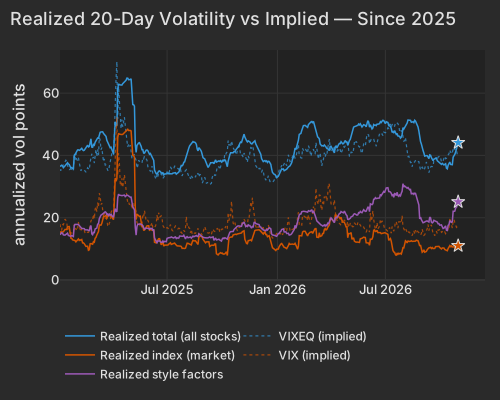
Realized correlation among stocks remains near its lows: 7.9% over 20 days, in the 3.5th percentile since 2020. The options market expects it to stay low. Implied correlation among the 50 largest S&P 500 stocks (Cboe COR1M) is 10.38, in the 4.8th percentile since 2006. That is how the top 50 high-beta names can fall 7% while the index falls only 1%. The movement is running through style exposures rather than the market as a whole.
Realized style volatility of 25.1 vol points (87.5th percentile) is more than twice the market's 11.0, while VIXEQ is at 40.15 and VIX at 18.44.
Realized 20-Day Volatility vs Implied — Since 2025
Series
Today Vol Pts
Prev Close Vol Pts
total
44.10
43.12
market
11.00
10.68
style
25.10
23.70
Economic Context
The third-quarter Employment Cost Index is due at 8:30 AM ET. Consensus expects a 0.8% quarterly rise, with annual compensation growth near 3.4%.
Factor Regime Reference
Variance decomposition: live intraday — 20261030 session, bracketed against its trailing-year range. Factor returns are trailing through last close. Total cross-sectional dispersion: 85%ile of the past year.
Variance mix — % of total, today vs 1d ago vs 1-yr avg
Variance explained — today vs. factor's trailing-year range
Marker = the factor's share of today's total variance, placed in its own trailing-year range (box 25–75%ile, ticks 90%ile and max). Amber marker = unusually load-bearing today (≥90%ile of its own year). Factor name green = up today / red = down.
Realized 20d vol (ann. pts): all stocks 44 vs VIXEQ 40 · index 11 vs VIX 18 · style factors 2588%ile
20-day window (19 completed days + today); percentiles vs model history since 2020; '3m' tokens rank vs the trailing 63 trading days; definitions in Terms below. Implied prints (Cboe) are delayed ~15 min. as of 07:21 ET
Top 50 high-beta momentum names (eq-wt, since-2020 rank): -7.2%1.5%ile · rest of market +0.0%
HF de-risking score (since-2020 rank so far today): 60%ile today · 32%ile 5-day · HF pain index 7.5σ below peak (7th-deepest of 32 since 2020), 13% won back · selling only: no short-covering leg
Trailing factor returns
Factor
Today
1d
5d
20d
60d
Style-Risk
Beta
-2.59%z-2.7
-1.26%
+0.26%
-12.37%
-8.28%
Residual Volatility
-0.34%z-0.7
-0.55%
-1.07%
-0.73%
+2.45%
International
+0.01%z+0.0
-0.26%
-1.09%
-0.89%
-0.48%
Style
Liquidity
-0.31%z-1.2
-0.15%
-0.28%
-0.57%
+1.99%
Value
-0.12%z-0.5
-0.17%
-0.49%
-0.65%
-0.39%
Growth
-0.06%z-0.3
-0.17%
-0.26%
-0.43%
-0.20%
Dividend Yield
+0.04%z+0.2
+0.17%
+0.50%
+0.03%
+0.59%
Size
-0.07%z-0.2
-0.82%
-1.00%
-0.88%
+1.76%
Profitability
+0.02%z+0.1
+0.42%
+0.15%
+0.98%
+0.15%
Leverage
-0.01%z-0.0
+0.50%
+0.96%
+0.12%
-2.29%
Style-Momentum
Medium-Term Momentum
+0.31%z+1.1
+0.04%
-1.38%
-1.36%
-1.25%
One-Day Momentum
+0.30%z+1.1
+0.13%
+0.51%
+0.28%
-2.90%
Short-Term Momentum
-0.26%z-0.9
+0.24%
-0.41%
+2.35%
+0.30%
Long-Term Momentum
-0.38%z-0.6
-0.53%
-0.01%
-3.43%
+0.39%
Style-Positioning
Hedge-Fund Ownership
-0.09%z-0.8
+0.12%
-0.10%
-0.18%
-0.63%
Short Interest
-0.06%z-0.3
-0.04%
-0.30%
+0.35%
-0.68%
Style-Flow
Morning Activity
+0.13%z+1.1
-0.21%
-0.17%
-0.21%
+0.38%
Short-Sale Activity
-0.03%z-0.3
+0.25%
-0.08%
+0.19%
+0.82%
Thematic
Semiconductors
-0.64%z-1.0
-0.06%
+1.21%
-4.50%
-2.83%
Bitcoin / Crypto
-0.27%z-0.9
-1.03%
-2.29%
-1.05%
+1.04%
Gold
+0.22%z+0.7
-0.29%
+0.20%
-0.93%
+1.43%
China
-0.16%z-0.4
-0.36%
-1.03%
-0.83%
-0.78%
Treasury (Duration)
-0.06%z-0.2
+0.48%
+0.52%
+1.88%
-1.40%
Oil
-0.00%z-0.0
-0.67%
-0.53%
-0.62%
+4.31%
5/20/60d windows include today's session; 1d is the previous session.
Terms
Factor z-score.Today's factor return divided by its daily-return standard deviation over ~1,600 trading days.
High-beta momentum cohort.US names above $2B market cap in the top quintile of both raw beta and 12-month momentum; membership frozen at each month's first business day. “Top 50” = the 50 strongest by combined rank.
HF de-risking score.A FactorPulse measure of de-risking in factor returns: the average of four legs, each in its own daily-volatility units and counted only when it moves in the de-risking direction. They are the most-shorted names rising, 12-month momentum winners falling, names crowded in hedge-fund 13F filings falling net of their beta and momentum, and last week's relative moves continuing instead of reverting (counted only alongside another leg). A leg counts as firing at half its daily volatility or more, so a leg can show a small value without firing. Types: A, covering and selling together; B, selling only; C, covering only. Ranked against every session since January 2020. It reads factor returns only, never positions.
Stock-specific (idiosyncratic) return.The part of a stock's move not explained by the market, style or thematic (industry and theme) factors in the FactorPulse risk model.
Data compiled by FactorPulse AI; edited and verified by Jeff Klein. For informational purposes only. Does not constitute financial advice, an investment recommendation, or an offer to buy or sell any securities. Always consult a qualified financial professional before making investment decisions.