President Luiz Inácio Lula da Silva's runoff victory in Brazil sent Brazilian shares trading in New York into a steep slide on Monday. Lula beat Flávio Bolsonaro by about 52% to 48% on Sunday to win a fourth term, overturning a first-round deficit, and Bolsonaro refused to concede on Monday. Brazilian stocks had rallied before the vote on polls that favored Bolsonaro. With Brazil's budget deficit nearing 10% of its economy and public debt above 82%, investors priced in heavier state intervention and a longer wait for central-bank rate cuts. Brokerage XP fell about 50%, bank Bradesco lost 30%, water utility Sabesp dropped 29% and lender Itaú Unibanco fell 21%. State-controlled oil company Petrobras slid 14% on worries about fuel-price controls, wiping out about $25 billion in market value.
At home, the S&P 500 rose 0.7% and the Nasdaq-100 gained 1.3%, with chipmakers in the lead after Anthropic filed for an IPO on the Nasdaq and reports said South Korean memory maker SK Hynix is weighing a roughly $12 billion special dividend. The semiconductor fund SMH rose 3% and Nvidia climbed 2.5%, adding about $127 billion in market value. Tesla jumped 6% after a Barclays upgrade and talk of a SpaceX merger, while Apple fell 1.4% after consumers reported screen cracks on its foldable iPhone Duo. Verizon dropped about 4% after missing revenue forecasts for a third straight quarter. Stocks most sensitive to market moves bounced back after a rough week for hedge funds: Goldman Sachs said its clients had their biggest retreat from individual-stock bets since late July in the week through Oct. 23. For more in-depth coverage, see our research note Factor Fingerprints of Hedge Fund Deleveraging Events. Microsoft, Alphabet and the Federal Reserve's rate decision all come Wednesday.
U.S. crude fell 1% to about $102 a barrel as top Saudi, Pakistani and Turkish officials met with Iranian counterparts in Tehran to try to head off a wider regional conflict. The 10-year Treasury yield held near 5% ahead of the Fed meeting. In energy deals, natural-gas producer EQT agreed to buy Appalachian rival Range Resources in an all-stock transaction worth more than $50 billion including debt for the combined company. Range shares jumped 17% and EQT slipped 1.7%, even as warm weather forecasts pushed U.S. natural-gas futures to a six-month low. Boeing and Coca-Cola report before Tuesday's opening bell.
Lula da Silva defeated Flávio Bolsonaro 51.8% to 48.2% on Sunday to win a fourth term, reversing a first-round deficit as Bolsonaro refused to concede on Monday NYT. With Brazil's fiscal deficit approaching 10% of GDP and public debt above 82% of GDP, investors priced in heavier state intervention and delayed central-bank easing bea.gov Financial Times. In New York trading, brokerage XP Inc. (XP) tumbled 49.5% (including a 41.4% stock-specific drop), Inter & Co. (INTR) lost 35.7%, Banco Bradesco (BBD) fell 29.9%, water utility Sabesp (SBS) shed 28.7%, and StoneCo (STNE) dropped 27.8%. Itaú Unibanco (ITUB) declined 21.0%, erasing $22.9B in market value, while state-controlled Petrobras (PBR) fell 14.3%, erasing $24.7B on fuel-price control concerns.
| Factor | Return | Z-Score | 5d Z | 20d Z | 63d Z | Category | Direction |
|---|---|---|---|---|---|---|---|
| Medium-Term Momentum | -0.87% | z=-3.1 | z=-1.2 | z=-0.7 | z=-0.3 | Style-Momentum | 1-month winners reversed |
| International | -0.71% | z=-2.4 | z=-1.5 | z=-0.8 | z=-0.1 | Style-Risk | US outperformed ADRs |
| China | -0.91% | z=-2.2 | z=-1.0 | z=-0.6 | z=-0.2 | Thematic | High China exposure lagged |
| Semiconductors | +1.08% | z=+1.8 | z=-0.1 | z=-1.4 | z=-0.5 | Thematic | Chip names outperformed |
| Residual Volatility | -0.59% | z=-1.2 | z=-0.0 | z=+0.0 | z=+1.3 | Style-Risk | Volatile names lagged |
| Beta | +1.06% | z=+1.1 | z=-0.9 | z=-2.2 | z=-0.4 | Style-Risk | High-beta names rebounded |
| Hedge-Fund Ownership | -0.08% | z=-0.7 | z=-2.0 | z=-0.9 | z=-0.5 | Style-Positioning | HF-owned names slightly lagged |
| Short Interest | -0.08% | z=-0.5 | z=+1.8 | z=+0.6 | z=-0.9 | Style-Positioning | Most-shorted slightly lagged |
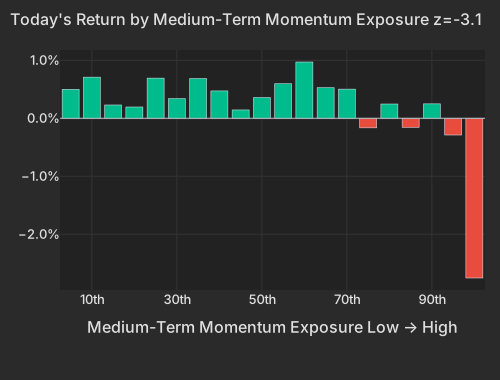
Because those Brazilian listings entered Monday among the strongest prior-month winners—XP carried a +4.7 exposure to 20-day momentum, Petrobras +2.9, and Itaú Unibanco +2.3—their selloff dragged the top bucket of 20-day momentum down 2.7% and accounted for 3.9% of total cross-sectional variance (above the 90th percentile of the past year). International fell 0.71% (z=-2.4) as US-headquartered companies outperformed US-listed foreign shares, while China dropped 0.91% (z=-2.2) as high-exposure biotech names such as Grail (GRAL) and Vaxcyte (PCVX, -1.8%) lagged.
| Bucket | Avg Ret Pct |
|---|---|
| 1 | 0.50 |
| 2 | 0.71 |
| 3 | 0.23 |
| 4 | 0.19 |
| 5 | 0.69 |
| 6 | 0.34 |
| 7 | 0.69 |
| 8 | 0.47 |
| 9 | 0.14 |
| 10 | 0.36 |
| 11 | 0.60 |
| 12 | 0.97 |
| 13 | 0.53 |
| 14 | 0.50 |
| 15 | -0.16 |
| 16 | 0.25 |
| 17 | -0.16 |
| 18 | 0.25 |
| 19 | -0.29 |
| 20 | -2.76 |
Earnings reactions so far todayReporters worth over $100 billion, or moving more than 10% with a value above $5 billion
| Company | Move | Stock-specific | Market cap | Revenue YoY | Margin YoY | What drove it |
|---|---|---|---|---|---|---|
| Verizon Communications VZ | -3.7% light volume | -4.4% | $186B | +1% | +1.2 pts operating | Third straight quarterly revenue miss despite EPS beat |
Stock-specific: the part of a stock's move not explained by the market, style or thematic (industry and theme) factors in the FactorPulse risk model.
Revenue and margin from the company's earnings release, year over year; margin change in percentage points; — where the release is not parsed or the figures failed checks.
Light volume: the company's earnings filing confirms the report, but trading volume has not caught up yet, so the move is an early read.
Of the 500 largest companies, 102 have reported (24% of market cap), on day 18 of the season.
How earnings reactions split, day 18 of the seasonThe 500 largest US companies with a confirmed earnings reaction so far (100), vs the same day in the past eight seasons and in four-season stretches back to mid-2020

| Season | ≤ −5σ | −5 to −2σ | −2 to 0σ | 0 to 2σ | 2 to 5σ | ≥ 5σ |
|---|---|---|---|---|---|---|
| This season | 4% | 24% | 30% | 21% | 16% | 4% |
| Past 8 seasons | 15% | 20% | 16% | 16% | 18% | 15% |
| Q2 2026 | 13% | 24% | 17% | 12% | 16% | 17% |
| Q1 2026 | 15% | 19% | 14% | 21% | 16% | 15% |
| Q4 2025 | 16% | 19% | 20% | 14% | 17% | 13% |
| Q3 2025 | 7% | 23% | 20% | 18% | 14% | 19% |
| Q2 2025 | 16% | 24% | 13% | 16% | 17% | 14% |
| Q1 2025 | 20% | 16% | 16% | 18% | 24% | 6% |
| Q4 2024 | 11% | 18% | 14% | 19% | 24% | 15% |
| Q3 2024 | 19% | 18% | 14% | 12% | 18% | 18% |
| Q3 '23–Q2 '24 | 14% | 20% | 15% | 14% | 19% | 17% |
| Q3 '22–Q2 '23 | 13% | 20% | 20% | 14% | 20% | 12% |
| Q3 '21–Q2 '22 | 14% | 20% | 12% | 19% | 25% | 10% |
| Q3 '20–Q2 '21 | 6% | 25% | 24% | 23% | 19% | 4% |
σ: a stock's earnings-day stock-specific move divided by its typical daily stock-specific move over the past year. Each bar is cut at the same business day of the season; companies weighted by the square root of market cap.
According to a Goldman Sachs Prime Brokerage note covering the week through Friday, October 23, reviewed by Reuters on Monday, systematic long/short funds fell 2% for their worst week since 2024 and fundamental long/short funds lost 1.1% as single stocks saw the largest de-grossing since late July. Goldman Sachs Prime Brokerage also recorded net selling of US equities for a third consecutive week and roughly $20B of technology-stock selling over the two weeks through October 23, approaching the $23B sold during July's episode, according to Reuters.
Our own measures show the pressure easing so far today rather than accelerating. While our HF de-risking score remains at the 97th percentile since 2020 over both five- and ten-day windows (rank 50 of 1,669 and 1,664 sessions, respectively, against full-day history), the one-day score has cooled to the 41.5th percentile so far today. The hedge-fund pain index sits 8.3 daily standard deviations below its October 6 peak—the seventh-deepest of 32 events since 2020—and has won back 12% of its loss since the October 22 low, with 1 of 7 legs (volatility) having confirmed a turn and beta, 12-month momentum, weekly reversal, volatility, and short-sale P&L moving back today. Five-day trend — Short-Term Momentum in the table — reversed today (-0.26%, z=-0.9) after two days of continuation. Meanwhile, Beta rose 1.06% (z=+1.1) against its 9.57% 20-day decline, and the top 50 high-beta momentum names gained 4.4% (94.2nd percentile since 2020; the broader ~190-name group rose 3.1%) while stocks outside the screen slipped 0.2%. Most-shorted stocks also paused their recent run, with Short Interest down 0.08% (z=-0.5) today after gaining 0.66% over five days.

| Date | Type | Most-shorted names up | 12-month winners down | 13F-crowded names down | Last week's moves continuing |
|---|---|---|---|---|---|
| 20261006 | B | 0.23 | 1.05 | 0.88 | 1.35 |
| 20261007 | — | 0.39 | 0.00 | 0.00 | 0.00 |
| 20261008 | — | 0.00 | 0.39 | 0.47 | 0.00 |
| 20261009 | — | 0.05 | 0.00 | 0.00 | 0.00 |
| 20261012 | C | 0.70 | 0.29 | 0.00 | 0.55 |
| 20261013 | C | 0.59 | 0.00 | 0.48 | 0.00 |
| 20261014 | B | 0.23 | 0.06 | 0.82 | 0.32 |
| 20261015 | A | 1.10 | 1.99 | 0.00 | 0.93 |
| 20261016 | B | 0.32 | 0.52 | 0.91 | 0.19 |
| 20261019 | C | 0.74 | 0.00 | 0.00 | 0.00 |
| 20261020 | C | 0.80 | 0.13 | 0.00 | 1.10 |
| 20261021 | B | 0.42 | 0.00 | 2.35 | 0.00 |
| 20261022 | A | 1.86 | 2.34 | 0.33 | 3.21 |
| 20261023 | B | 0.04 | 0.00 | 1.42 | 0.58 |
| 20261026 | B | 0.00 | 0.00 | 0.66 | 0.00 |
Background: our research note Factor Fingerprints of Hedge Fund Deleveraging Events compares October with 31 hedge-fund deleveraging events since 2020.
Semiconductors led thematic factors at +1.08% (z=+1.8), lifting memory and chip funds ahead of Wednesday's earnings from Microsoft (MSFT, +1.4%) and Alphabet (GOOGL, -1.0%). Sentiment received a boost after Anthropic filed an S-1 for a Nasdaq IPO and reports indicated SK Hynix is reviewing a 16 trillion won ($12B) special dividend funded by its Kioxia stake sale alongside Wednesday's results Economic Times Economic Times. Nvidia (NVDA) climbed 2.5%, adding $126.6B in market value largely through its factor exposures, while optical and chip suppliers Lumentum (LITE, +9.6%), Viavi Solutions (VIAV, +6.8%), and Semtech (SMTC, +4.8%) rallied.
That windfall among hardware suppliers contrasts with tightening financing conditions for AI borrowers and private lenders. Morgan Stanley strategists James Egan and Carolyn Campbell noted that AAA data-center asset-backed security spreads have widened to roughly 200 bps amid heavy AI infrastructure issuance Bloomberg. In private credit, Blackstone Secured Lending Fund (BXSL) fell 1.6% at 2.1× its typical session volume pace after Citizens JMP initiated coverage at Market Perform, projecting a dividend reduction toward $0.65 from $0.77 after second-quarter net investment income of $0.75 covered 97% of the payout Robinhood, according to Yahoo Finance. Peer Ares Capital (ARCC) edged down 0.2% ahead of Tuesday's report. Among mega-cap movers, Tesla (TSLA) gained 5.9% (+4.6% stock-specific, adding $86.6B in market value) after a Barclays upgrade and SpaceX merger speculation pushed bearish analyst ratings to an 11-year low, while Apple (AAPL) fell 1.4% (-2.8% stock-specific) following consumer reports of screen fractures on its foldable iPhone Duo Bloomberg Bloomberg.
| ETF | Theme | Today | 1d Ago | 5d Ago | 20d Ago | 63d Ago |
|---|---|---|---|---|---|---|
| DRAM | memory chips & storage | +3.6% | +3.0% | +1.3% | -24.0% | -10.2% |
| SMH | semiconductors | +3.3% | +0.7% | -2.3% | -13.1% | -3.9% |
| AIPO | AI power infrastructure | +2.4% | -1.4% | -6.8% | -16.7% | -17.2% |
| XAR | defense | +2.3% | -0.2% | -3.0% | -9.1% | -20.2% |
| QQQ | large cap growth | +1.3% | -0.01% | -0.8% | -5.4% | +3.4% |
| SPY | large cap | +0.7% | -0.5% | -0.4% | -1.5% | +3.1% |
| IWD | large and mid cap value | +0.2% | -0.6% | +0.7% | +2.2% | +3.5% |
| USO | oil | -1.2% | +4.3% | +4.8% | +14.3% | +35.9% |
| BXSL | loans of private companies | -1.6% | -2.4% | -2.2% | -2.4% | +4.7% |
| XLC | communication services | -1.6% | -1.8% | -4.4% | -6.6% | -1.7% |
WTI crude retreated 1.0% to $102.22 at 2:59 PM ET as Saudi Defense Minister Prince Khalid bin Salman, Pakistani Army Chief Asim Munir, and Turkish Intelligence Chief Ibrahim Kalin met Iranian officials in Tehran to prevent broader regional conflict CNBC Financial Times. Even as oil pulled back, the 10-year Treasury yield edged up 0.2 bps to 4.99% and the 2-year yield rose 3.6 bps to 4.718% ahead of Wednesday's FOMC decision Federal Reserve CNBC CNBC. Over the past two weeks through Friday's close, USO rose 14.4% while the 10-year yield fell 24.5 bps (putting their 20-day co-movement in the 3rd percentile since 2019), whereas SMH fell 12.6% alongside lower yields (96th percentile since 2019). That shift indicates the bond market is trading growth and AI hardware expectations rather than oil-driven inflation.
Within energy and cyclicals, EQT Corp. (EQT, -1.7%) agreed to acquire Appalachian peer Range Resources (RRC) in an all-stock deal at 0.987 EQT shares per Range share, creating a combined producer with pro forma enterprise value above $50B Financial Times, according to Yahoo Finance. Range surged 17.4% (+18.0% stock-specific) even as warm US weather forecasts pushed domestic natural gas futures to a six-month low Financial Times. Broader cyclical and power-infrastructure funds bounced slightly today after steep 20-day drawdowns through Friday's close that left uranium (URA, -16.6% over 20 sessions, 3.8th percentile since late 2018), nuclear power (NLR, -14.6%, 2.6th percentile), and smart-grid infrastructure (GRID, -9.4%, 3.2nd percentile) in the bottom 4% of their 20-day windows since late 2018. Attention now turns to earnings from Welltower (WELL, +0.8%) and Nucor (NUE, +0.7%) after today's close, followed by Boeing (BA), S&P Global (SPGI, -0.2%), Corning (GLW), and Coca-Cola (KO) before Tuesday's open.
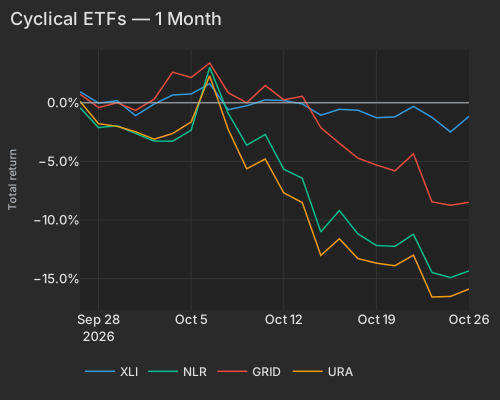
| T | XLI | NLR | GRID | URA |
|---|---|---|---|---|
| 2026-09-25 | 0.95 | -0.41 | 0.73 | 0.12 |
| 2026-09-28 | -0.03 | -2.12 | -0.41 | -1.79 |
| 2026-09-29 | 0.18 | -1.96 | 0.01 | -2.01 |
| 2026-09-30 | -1.10 | -2.60 | -0.65 | -2.47 |
| 2026-10-01 | -0.11 | -3.27 | 0.30 | -3.11 |
| 2026-10-02 | 0.66 | -3.28 | 2.61 | -2.62 |
| 2026-10-05 | 0.75 | -2.34 | 2.16 | -1.64 |
| 2026-10-06 | 1.63 | 3.02 | 3.39 | 2.30 |
| 2026-10-07 | -0.59 | -0.89 | 0.86 | -2.28 |
| 2026-10-08 | -0.25 | -3.62 | -0.00 | -5.63 |
| 2026-10-09 | 0.25 | -2.70 | 1.48 | -4.80 |
| 2026-10-12 | 0.19 | -5.67 | 0.25 | -7.68 |
| 2026-10-13 | -0.09 | -6.44 | 0.56 | -8.52 |
| 2026-10-14 | -1.06 | -11.01 | -2.12 | -13.02 |
| 2026-10-15 | -0.56 | -9.19 | -3.45 | -11.60 |
| 2026-10-16 | -0.63 | -11.18 | -4.72 | -13.29 |
| 2026-10-19 | -1.27 | -12.17 | -5.31 | -13.68 |
| 2026-10-20 | -1.20 | -12.25 | -5.81 | -13.90 |
| 2026-10-21 | -0.31 | -11.21 | -4.35 | -13.00 |
| 2026-10-22 | -1.24 | -14.48 | -8.45 | -16.57 |
| 2026-10-23 | -2.49 | -14.91 | -8.74 | -16.52 |
| 2026-10-26 | -1.16 | -14.34 | -8.49 | -15.89 |
The Dallas Fed Manufacturing Survey, released at 10:30 AM ET, showed the headline general business activity index rising to 13.4 in October from 9.8, beating the 7.0 consensus forecast even as the production index dropped 14 points to 15.8 and new orders slowed to 9.3. Raw material prices climbed to 55.3 while wages and benefits cooled to 20.8, and the US Dollar Index (DXY) edged up 0.2% to 101.99 at 3:10 PM ET CNBC.
Variance decomposition: live intraday — 20261026 session, bracketed against its trailing-year range. Factor returns are trailing through last close. Total cross-sectional dispersion: 77%ile of the past year.
Variance mix — % of total, today vs 1d ago vs 1-yr avg
market 23%ile style 56%ile thematic 88%ile idiosyncratic 58%ile
Variance explained — today vs. factor's trailing-year range
Marker = the factor's share of today's total variance, placed in its own trailing-year range (box 25–75%ile, ticks 90%ile and max). Amber marker = unusually load-bearing today (≥90%ile of its own year). Factor name green = up today / red = down.
Correlation & dispersion — realized vs implied
Pairwise realized correlation (20d): 8.17% 4.3%ile since 2020 · 35%ile 3m most extreme since 2026-09-09
Top-500 pairwise: 10.14% 8.5%ile since 2020 · 40%ile 3m · implied (Cboe COR1M): 10.46 4.8%ile since 2006 (gap -0.3pp)
Realized 20d vol (ann. pts): all stocks 41 vs VIXEQ 42 · index 10 vs VIX 18 · style factors 22 82%ile
20-day window (19 completed days + today); percentiles vs model history since 2020; '3m' tokens rank vs the trailing 63 trading days; definitions in Terms below. Implied prints (Cboe) are delayed ~15 min. as of 14:58 ET
Top 50 high-beta momentum names (eq-wt, since-2020 rank): +4.4% 94.2%ile · rest of market -0.2%
HF de-risking score (since-2020 rank so far today): 42%ile today · 97.0%ile 5-day · HF pain index 8.3σ below peak (7th-deepest of 32 since 2020), 12% won back · selling only: no short-covering leg
| Factor | Today | 1d | 5d | 20d | 60d |
|---|---|---|---|---|---|
| Style-Risk | |||||
| International | -0.71% z-2.4 | +0.24% | -1.00% | -0.99% | -0.82% |
| Residual Volatility | -0.59% z-1.2 | +0.34% | -0.04% | +0.10% | +3.68% |
| Beta | +1.06% z+1.1 | +0.22% | -1.96% | -9.57% | -4.59% |
| Style | |||||
| Dividend Yield | +0.26% z+1.5 | +0.22% | +0.76% | -0.29% | +0.38% |
| Value | -0.27% z-1.2 | -0.12% | -0.84% | +0.11% | -0.52% |
| Size | +0.21% z+0.6 | +0.04% | -0.81% | +0.41% | +2.84% |
| Liquidity | -0.11% z-0.4 | -0.35% | -0.13% | -0.79% | +2.20% |
| Growth | +0.05% z+0.2 | -0.09% | -0.45% | -0.07% | +0.54% |
| Profitability | -0.01% z-0.1 | -0.38% | -0.34% | +1.02% | -0.41% |
| Leverage | -0.01% z-0.0 | -0.01% | +0.17% | -1.16% | -3.92% |
| Style-Momentum | |||||
| Medium-Term Momentum | -0.87% z-3.1 | -0.04% | -0.75% | -0.90% | -0.95% |
| Short-Term Momentum | -0.26% z-0.9 | +0.21% | +1.18% | +2.46% | -0.36% |
| Long-Term Momentum | +0.54% z+0.8 | +0.66% | -0.25% | -2.02% | -0.62% |
| One-Day Momentum | +0.12% z+0.4 | -0.26% | -0.09% | -0.14% | -3.58% |
| Style-Positioning | |||||
| Hedge-Fund Ownership | -0.08% z-0.7 | -0.18% | -0.49% | -0.46% | -0.51% |
| Short Interest | -0.08% z-0.5 | -0.07% | +0.66% | +0.46% | -0.58% |
| Style-Flow | |||||
| Morning Activity | -0.15% z-1.2 | +0.15% | -0.13% | -0.68% | +0.72% |
| Short-Sale Activity | -0.09% z-0.8 | +0.01% | +0.09% | +0.12% | +1.08% |
| Thematic | |||||
| China | -0.91% z-2.2 | +0.15% | -0.93% | -1.13% | -0.76% |
| Semiconductors | +1.08% z+1.8 | +0.48% | -0.16% | -3.85% | -3.77% |
| Bitcoin / Crypto | -0.49% z-1.6 | +0.34% | +0.87% | +0.59% | +2.45% |
| Gold | -0.32% z-1.0 | -0.18% | -1.53% | -2.22% | +1.75% |
| Oil | +0.37% z+0.8 | +1.08% | +0.33% | +0.87% | +4.77% |
| Treasury (Duration) | -0.16% z-0.5 | -0.29% | +1.13% | +0.39% | -2.34% |
5/20/60d windows include today's session; 1d is the previous session.
Pairwise realized correlation. Index variance net of the weighted idiosyncratic diagonal, over the cross terms — the estimator used for implied-correlation indices. 20-day window unless noted; history since 2020.
Market variance share. The fraction of cross-sectional variance explained by the market factor — the attribution companion to pairwise correlation, not a substitute for it.
Factor z-score. Today's factor return divided by its daily-return standard deviation over ~1,600 trading days.
Conditional importance. A factor's relative share of what a tree-based fit of today's stock returns explains; sums to 100% across factors.
High-beta momentum cohort. US names above $2B market cap in the top quintile of both raw beta and 12-month momentum; membership frozen at each month's first business day. “Top 50” = the 50 strongest by combined rank.
HF de-risking score. A FactorPulse measure of de-risking in factor returns: the average of four legs, each in its own daily-volatility units and counted only when it moves in the de-risking direction. They are the most-shorted names rising, 12-month momentum winners falling, names crowded in hedge-fund 13F filings falling net of their beta and momentum, and last week's relative moves continuing instead of reverting (counted only alongside another leg). A leg counts as firing at half its daily volatility or more, so a leg can show a small value without firing. Types: A, covering and selling together; B, selling only; C, covering only. Ranked against every session since January 2020. It reads factor returns only, never positions.
Dispersion (realized). Total cross-sectional volatility net of the market component; high dispersion is the flip side of low correlation.
Stock-specific (idiosyncratic) return. The part of a stock's move not explained by the market, style or thematic (industry and theme) factors in the FactorPulse risk model.
VIXEQ / DSPX / COR1M. Cboe implied indices: single-stock volatility, dispersion, and 1-month implied correlation (top-50 S&P names). Quotes delayed ~15 minutes.
Data compiled by FactorPulse AI; edited and verified by Jeff Klein. For informational purposes only. Does not constitute financial advice, an investment recommendation, or an offer to buy or sell any securities. Always consult a qualified financial professional before making investment decisions.
For more on factor construction methodology, see www.factorpulse.com/glossary.